The Four-Part Test Insurance Companies Use
Insurance companies apply the catastrophic ground cover collapse four-part test rigidly. Understanding each requirement helps fight denials.
Abrupt Collapse Requirement: Insurance companies claim most ground movement is gradual. They analyze when cracks first appeared, when doors started sticking, when depressions formed. Any evidence of progressive damage becomes proof of gradual subsidence.
We document that surface manifestations often lag behind subsurface collapse. Underground voids can form suddenly even if surface impacts appear gradual. Proper geotechnical investigation proves timing of actual collapse.
Visible Depression Requirement: Insurance companies claim no depression is visible if sinkholes are under buildings. They argue you must see the actual void, not just damage symptoms.
We prove depressions are visible through engineering analysis. Ground surveys show surface elevation changes. Before and after photographs document depression development.
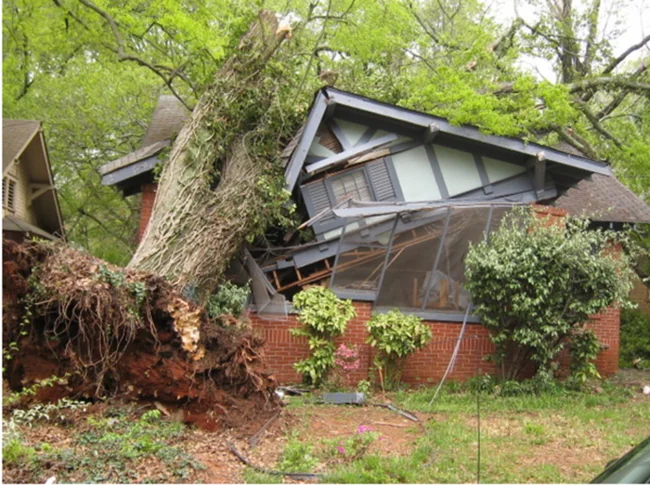
Foundation Damage Requirement: Insurance companies narrowly interpret "foundation." They claim damage to walls, floors, or roofs doesn't qualify. Only the actual foundation structure counts.
We bring structural engineers who document foundation damage specifically. We prove connection between foundation damage and underlying collapse.
Condemnation Requirement: This is the most difficult requirement to meet. Most damaged buildings don't reach condemnation level but still require expensive repairs.
We work with building officials to obtain proper condemnation orders when warranted. We document why buildings are unsafe for occupancy even if formal condemnation orders aren't issued.
Commercial Sinkhole Claims
Commercial properties face unique sinkhole challenges. Larger buildings suffer more extensive damage. Parking lots and site improvements represent significant investments.
Business interruption from sinkhole damage can exceed structural repair costs. Properties may be closed for months during investigation and repair. Lost revenue accumulates quickly.
Commercial policies often have different sinkhole coverage provisions than residential policies. Some exclude sinkholes entirely. Others include catastrophic ground cover collapse with commercial-specific definitions.
We handle commercial sinkhole claims including retail properties, office buildings, industrial facilities, and multi-family residential buildings.