The New York Earthquake Risk Nobody Talks About
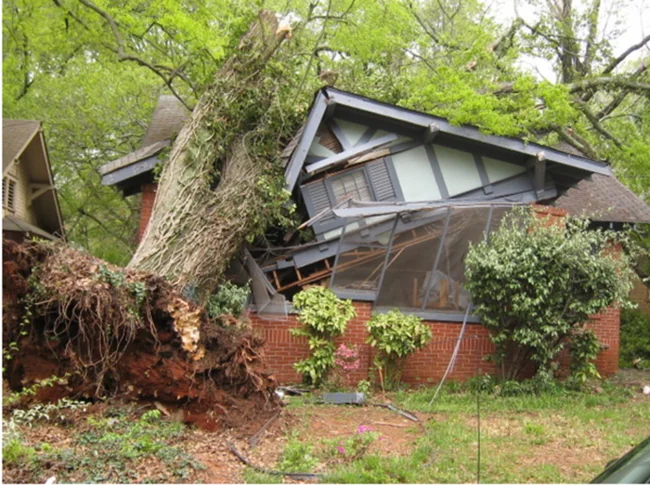
A magnitude 4.8 earthquake struck the region in April 2024. It was felt across New York City and Long Island. Buildings shook. People evacuated. Damage occurred.
Most New York residents had no earthquake insurance. They didn't think they needed it. Earthquakes happen in California, not New York.
New York has active fault lines. The Ramapo Fault System runs through parts of New York. Historic earthquakes have struck the region for centuries.
East Coast earthquakes affect larger geographic areas than West Coast earthquakes. Different geology transmits seismic waves farther. A moderate earthquake centered hundreds of miles away can still damage New York buildings.
Most New York buildings were constructed without seismic standards. Older buildings with unreinforced masonry, weak connections, and brittle materials are particularly vulnerable.
Hidden Earthquake Damage Insurance Companies Miss
Visible earthquake damage is obvious. Cracks in walls. Collapsed chimneys. Broken windows. Insurance adjusters document these easily.
Hidden damage is where insurance companies save money. They don't investigate. They don't use specialized equipment. They don't bring structural engineers.
Hidden damage includes foundation cracks concealed by landscaping or finishes. Structural damage inside walls not visible from interior or exterior. Shifted framing members that compromise structural integrity. Broken connections between building elements. Utility damage that hasn't yet manifested as leaks or failures.
We bring structural engineers who use specialized equipment. Crack monitors measure ongoing movement. Laser levels detect subtle shifts. Borescopes inspect inside walls without demolition. Ground-penetrating radar identifies subsurface damage.
This hidden damage often exceeds visible damage costs. Insurance companies don't document it because they don't look for it.
Common Earthquake Claim Denials
- Pre-Existing Damage Denial: Insurance companies claim damage existed before the earthquake. Every old crack becomes evidence. They deny new damage by calling it old.
- Cosmetic Damage Denial: They classify all cracks as cosmetic, not structural. They claim repairs are not covered because damage isn't structural.
- Maintenance Denial: They argue damage resulted from lack of maintenance, not the earthquake. Poor maintenance becomes a reason to deny claims.
- Below Deductible Denial: They claim damage doesn't exceed your deductible. They manipulate estimates to push you below the threshold.
- Excluded Damage Denial: They claim damage falls under policy exclusions. Code upgrades, landscaping damage, indirect losses all become excluded items.
We fight these denials with engineering evidence and policy interpretation. Many are improper and can be overturned.